Nico Pod Store
Curated · Label facts · Reviews planned
We don't tell you taste.We tell you everything else.
Strength, format, pouch count. Product pages show manufacturer and label facts; named reviews are planned for when our reviewer programme opens. Pouches from $1.49 / can.
Featured pouches
A signature SKU from every brand we carry. From single can to 30-pack — every product page shows the per-can math.
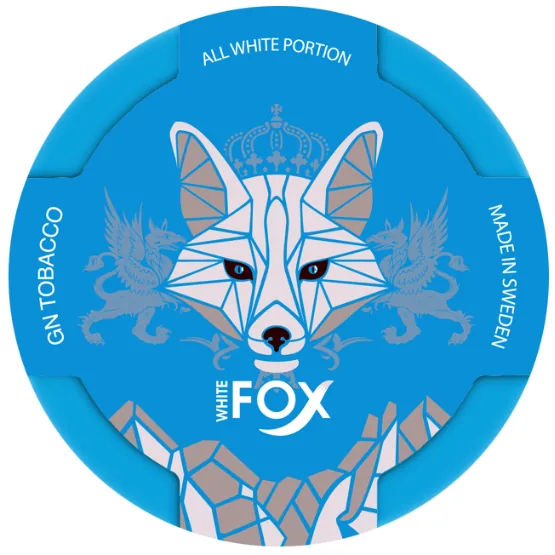
White Fox
Original · strength not published
From €4.09 / can
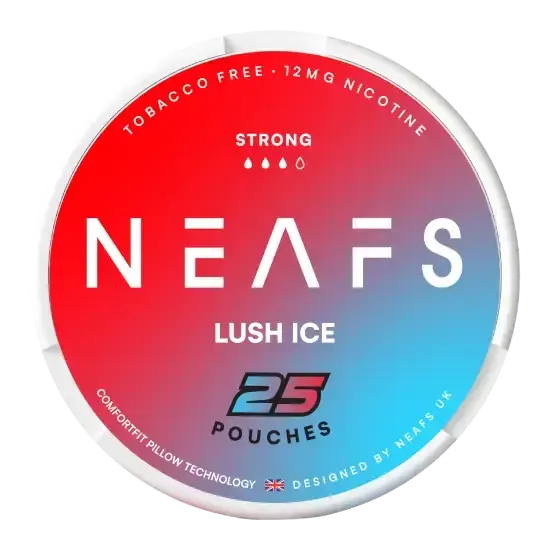
NEAFS
Lush Ice · ≈12 mg/g
From €3.27 / can
Klint
Apple Mint · ≈16 mg/g
From €3.27 / can
Cuba
Mint Fresh · 30 mg/g
From €2.86 / can
77
Ice Mint · ≈8 mg/g
From €2.45 / can
CLEW
Cool Mint · 10 mg per pouch
From €2.04 / can
NEAFS
Menthol · ≈16 mg/g
From €3.27 / can
NEAFS
Mint Fusion · ≈12 mg/g
From €3.27 / can
Brands we curate
Every brand page sets out the manufacturer's facts and how we plan to review the brand: strength, comfort, duration, drip, kick. Not taste.
View all brands →- View Klint →Klint3 variants
Tobacco-free pouches made in Sweden — broad mint and fruit range.
- View 77 →775 variants
Medium-strength pouches with a separate GHOST mini sub-line.
- View Cuba →Cuba3 variants
Ninja series — coconut, mint-fresh, piña colada.
- View White Fox →White Fox3 variants
Made in Sweden by Swedish Smokeless, formerly GN Tobacco.
- View CLEW →CLEW6 variants
Six flavours, one strength tier — 10mg per pouch.
- View NEAFS →NEAFS18 variants
Tobacco-free pouch line in Regular / Strong / Extra Strong tiers.
- View STNG →STNGApparel
Apparel — sweatshirts and tees.
The US white-pouch market
Why functional honesty matters in a market still finding its feet
The American nicotine-pouch market is younger than most shoppers realise. Pouches went from niche white-label imports to a category visible at every gas-station counter inside a five-year window, and the editorial conventions of the wider snus world never crossed the Atlantic with them. We built Nico Pod Store around the gap that opened up there.
A young market, growing fast
Nicotine pouches as a US retail category effectively begin with Swedish Match's PMTA-cleared ZYN launch and the post-2020 demand spike that followed. Before that window, pouches were a niche product for ex-smokers and Scandinavian expats; after it, the category became the fastest-growing segment of the broader nicotine market. Most American shoppers come to white pouches sideways — they arrive from cigarettes, from disposable vapes, or from dipping tobacco — rather than from a pre-existing snus culture. Their reference frame for what a pouch should feel like is being assembled in real time, one purchase at a time.
That trajectory matters for how content is written about pouches. Sweden's mature market produced retailers, reviewers, and shoppers who shared a common vocabulary for kick, comfort, duration, drip, and discreteness because tobacco snus had taught everyone those terms long before white pouches existed. The United States has no equivalent baseline. The default editorial register here is marketing prose — flavour adjectives, lifestyle imagery, brand-funded influencer reviews — and it does not give a first-time pouch buyer the information they actually need to pick something that works for them.
FDA scrutiny is increasing
The regulatory picture is also moving. The FDA's premarket tobacco product authorisation pathway has cleared a small set of pouch brands and continues to evaluate others; the agency's enforcement focus on flavoured pouches, youth-appeal marketing, and unauthorised imports has stepped up since 2023. State-level rules layer on top: Massachusetts restricts flavoured pouches, several states require online age verification, and a handful are debating tobacco-21 enforcement provisions that already cover combustible products. The compliance landscape is more demanding than it was three years ago and is moving toward the European model on most axes.
We treat that direction of travel as a feature rather than a problem. Pages on Nico Pod Store carry server-rendered structured data, age verification at checkout, no taste claims that the FDA could read as misleading flavour marketing, and, once reviews exist, named bylines rather than influencer placements. That posture is built for the regulatory environment the United States is moving toward, not the one it is leaving.
How we curate for the US shopper
Our curation starts from a different question than the Amazon-style mass catalogues. Instead of asking which brands have the volume to fill a search-results page, we ask which brands have a coherent range that the eight functional dimensions we plan to review can say something useful about: kick intensity, kick onset, lip comfort, duration in minutes, drip volume, moisture retention, discreteness, and build quality. The catalogue is smaller as a result — six pouch brands at launch — and the per-can math is published on every product page across the 1, 5, 10, and 30-pack ladders, so the value comparison is not buried in promo copy.
No reviews are published yet, so no product page carries rating markup. AggregateRating structured data will appear on a product page only after that product has at least one real named-reviewer assessment on file. No fake stars, no seeded ratings, no anonymous editorial voice, no marketing copy disguised as reviews. The eight-dimension framework is the editorial spine; everything else is operations.